How much does your private bank really cost you?
Private banking fees are never billed as a single invoice: they are scattered across statements, trade confirmations, fund prospectuses, and life insurance terms. Most clients remember the rate of their mandate, around 1% per year, and leave it at that.
In reality, the total cost is closer to 2% to 3% per year. On two million euros invested over twenty years, the difference amounts to several hundred thousand euros.
All the figures are in your documents, but they are spread out. This article shows how to gather them, with a worked example and the questions to ask your banker.
In brief
- The full cost of private banking is split into four layers: the institution, the products, the insurance wrapper, and implicit margins.
- The annual cost and charges statement, mandatory since 2018, is the starting point, but it ignores life insurance and implicit margins.
- The method can be summed up in one sentence: convert everything into euros over twelve months, then into a percentage of the average balance, layer by layer.
- In our typical case of two million euros, the client thinks they are paying €20,000 and is actually paying €52,260, or 2.6% of the balance.
- Explicit fees can be negotiated; product fees can be reduced by demanding share classes without retrocessions and by questioning every layer.
Why no statement shows the total cost as a single figure
No document consolidates the cost of a private banking relationship because three families of fees coexist in different documents. The bank sells a service, products, and often an insurance wrapper: each level has its own fee schedule and issuer.
Table 1. The three families of fees and where to find them (2026)
Source: standard regulatory documents from the French market, 2026 summary.
What the annual statement provides, and what it leaves out
The annual cost and charges statement, mandated by the European MiFID II directive (Markets in Financial Instruments Directive) since 3 January 2018, is the starting point. It presents the costs of services, instruments, and payments received from third parties in both euros and percentages.
It remains incomplete in three respects: it ignores insurance contracts, poorly measures implicit margins, and does not detail its totals line by line.
The five-step method for reconstructing your invoice
Reconstructing the total cost is within the reach of any client who dedicates a few hours to it.
- Gather the documents : tariff brochure, mandate or advisory agreement, annual statement of costs and charges, trade confirmation, key information document for each fund, and the insurance contract fee schedule.
- Classify each fee into one of the four layers detailed below.
- Convert each fee into euros over twelve months, including all taxes, then as a percentage of the average outstanding amount.
- Add up the layers to obtain the total annualised cost.
- Compare this cost to the net return obtained, according to the net performance calculation method detailed elsewhere, and to the cost of a comparable solution.
Layer 1: fees charged by the institution
The first layer includes what the institution deducts directly, and despite its visibility, it can still hold surprises.
Discretionary management and advisory: watch out for pre-tax amounts
Individual discretionary management is subject to VAT at the standard rate of 20%unlike collective fund management, which is exempt (Article 261 C of the General Tax Code). A fee schedule displayed at 1% excluding tax, a common occurrence in brochures, therefore corresponds to 1.2% actually charged.
Advisory mandates follow the same logic. Fixed fees are more transparent, provided that any retrocessions on products are returned to the client.
Good to know. An annual minimum billing amount often applies regardless of the assets under management. For a portfolio that is modest relative to the institution's thresholds, this floor alone can exceed 2%. This is mentioned in the fee brochure, but never in the management report.
Custody, brokerage and foreign exchange
Custody fees
These often include a minimum charge per line, which penalises portfolios spread across many small positions.
Brokerage
This is added to mandate fees, even though the manager alone decides on the number of transactions. A 50% turnover rate at 0.6% brokerage adds 0.3% in annual costs, and the turnover rate does not appear on any statement.
Foreign exchange margin
Every foreign currency transaction uses a conversion rate that includes a margin, without a separate line item for the charge. It can be measured by comparing the transaction advice to the market rate at the time.
Table 2. Ranges commonly observed in private banking (France, 2026)
Source: French market fee brochures, 2026 summary. Indicative ranges.
Layer 2: fees embedded within products
The second layer is the heaviest in the majority of portfolios and the least visible: deducted from within the products before their value is calculated, it only appears as reduced performance.
Ongoing fund charges
An actively managed equity fund typically displays ongoing charges of between 1.5% and 2.2% per year in its key information document, plus its transaction costs and any potential performance fee.
Retrocession fees: the first line to check
Retrocession fees are the rebates that an asset management company pays to the distributor of its funds. Since MiFID II, firms cannot retain these in either discretionary management or independent advisory services.
In non-independent advisory services, the model used by most French private banks, they can retain them provided they are declared: this is the "payments received from third parties" line on your annual statement.
"It’s as if you went to see a doctor and paid for the consultation based on the medication they prescribed you. No matter how honest the doctor or private advisor is, there is a bias. You pay a doctor for their advice, regardless of the products. Why shouldn't it be the same in private wealth management?"
Pierre Marin, co-founder and CEO of RockFi, interview with La Martingale.
Three structures to examine closely
Les In-house funds keep the margin within the group without paying any retrocession: they avoid the "payments received from third parties" line with the same effect.
Les Structured products build their margin into the issue price, typically 1% to 3% of the amount invested, with no deduction line shown.
Le Private equity often stacks target funds, feeder funds, and firm fees on capital locked away for eight to ten years, a structure detailed in our white paper on Private Equity.
At the other end of the spectrum, index funds
ETFs, those listed funds that track an index, have average fees of around 0.20% per year, whereas active management sits between 1% and 2%. Over fifteen years, only about 12% of US managers beat the S&P 500 according to the SPIVA study.
Our white paper on ETFs explains how to select them.
Layer 3: the life insurance wrapper adds its own tier
A large proportion of private banking assets is held within a life insurance policy, a capitalisation contract, or a retirement savings plan. This wrapper levies its own layer: on average 0.73% per year in management fees according to France Assureurs (2025 data), plus any potential entry or switching fees.
Since the decree of 24 February 2022, every insurer has been required to publish a standardised fee table online. The total per unit-linked fund, including both contract and underlying asset fees, has been included in pre-contractual and annual disclosures since 1 July 2022. This is the most useful document in this layer.
Two cases to watch
In Luxembourg life insurance, the dedicated internal fund combines the fees of the insurer, the manager, the custodian bank, and the underlying assets: four levels, each of which must be justified by an identifiable service.
The euro fund, meanwhile, publishes a return net of management fees: the deduction is real, but never expressed in euros.
Layer 4: costs that do not appear in any document
Some costs can only be calculated by reconstructing the transactions.
Unremunerated cash
8% of a portfolio left at a zero rate in a cash account, when the European Central Bank's deposit facility offers 2.25% since 17 June 2026, represents an annual shortfall of approximately 0.18% of assets under management.
Bond margins and placement commissions
Bonds purchased over-the-counter carry a margin embedded in the execution price, with no apparent brokerage fee. Placement commissions on the primary market are paid by the issuer.
The tax cost of turnover
Every trade in a securities account crystallises a taxable capital gain. While not a fee, it reduces net capital just as a fee would.
Case study: a breakdown of the costs for a two-million-euro portfolio
Let’s take a hypothetical client: €2,000,000 split between a €1,200,000 discretionary managed securities account and an €800,000 Luxembourg life insurance policy with a dedicated internal fund. They believe they are paying 1% in fees, or €20,000 per year.
Table 3. Breakdown of annual costs for the case study (2026 projections)
Source: representative projections, 2026. Hypothetical example.
The total comes to €52,260, or 2.6% of assets under management : the client is paying two and a half times what they think they are paying.
What the client thinks they pay versus what they actually pay
The first chart compares perception with reality.
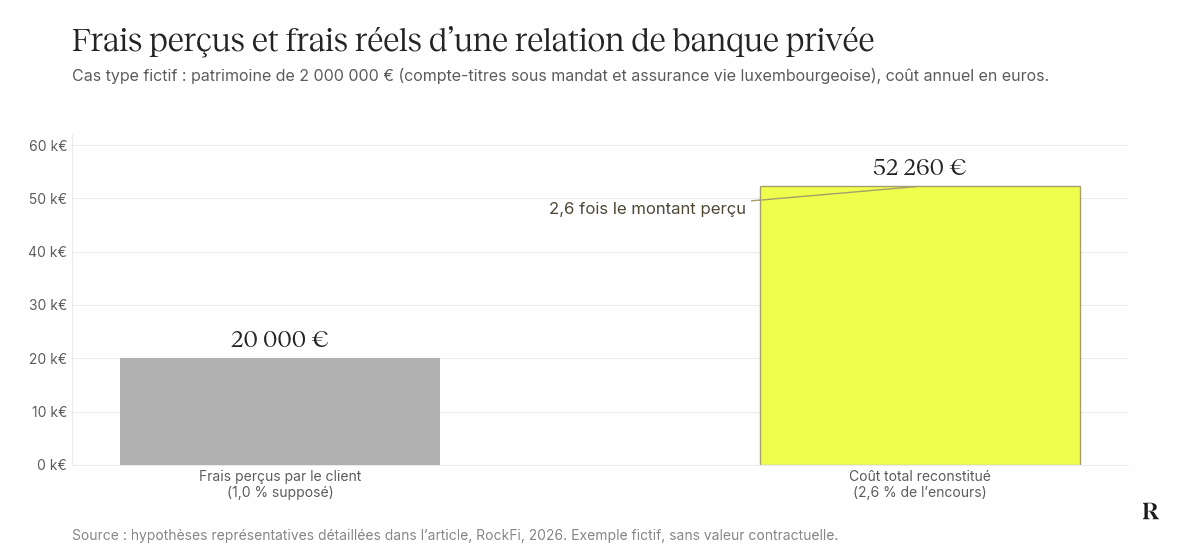
Where the costs come from: a layer-by-layer analysis
The institution's explicit fees account for barely more than a third of the total; the rest comes from the products, the wrapper, and implicit margins.
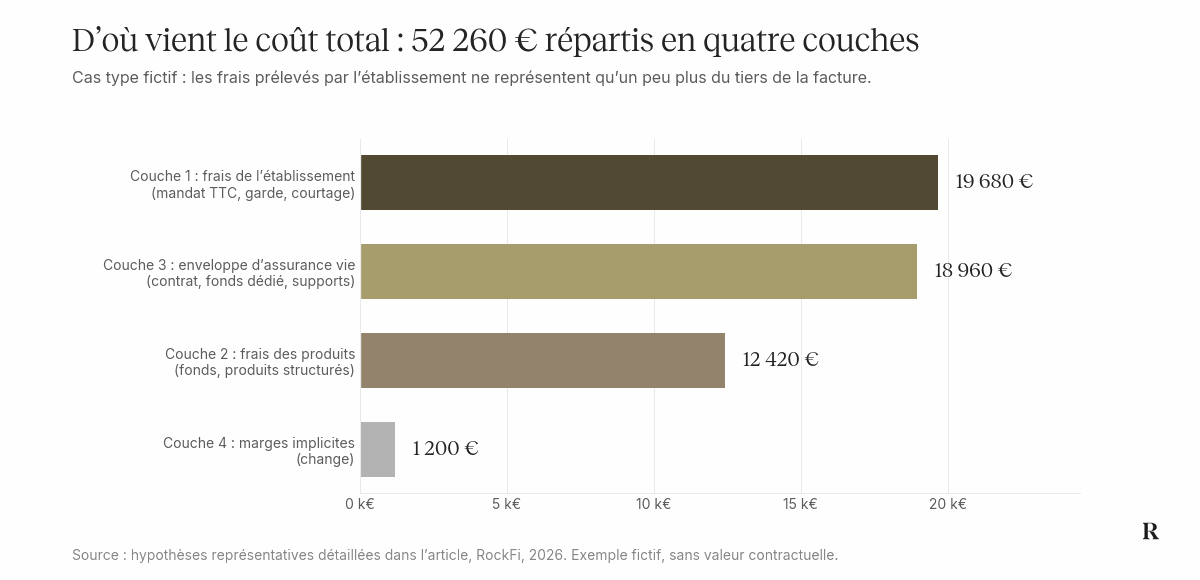
The long-term impact runs into the millions
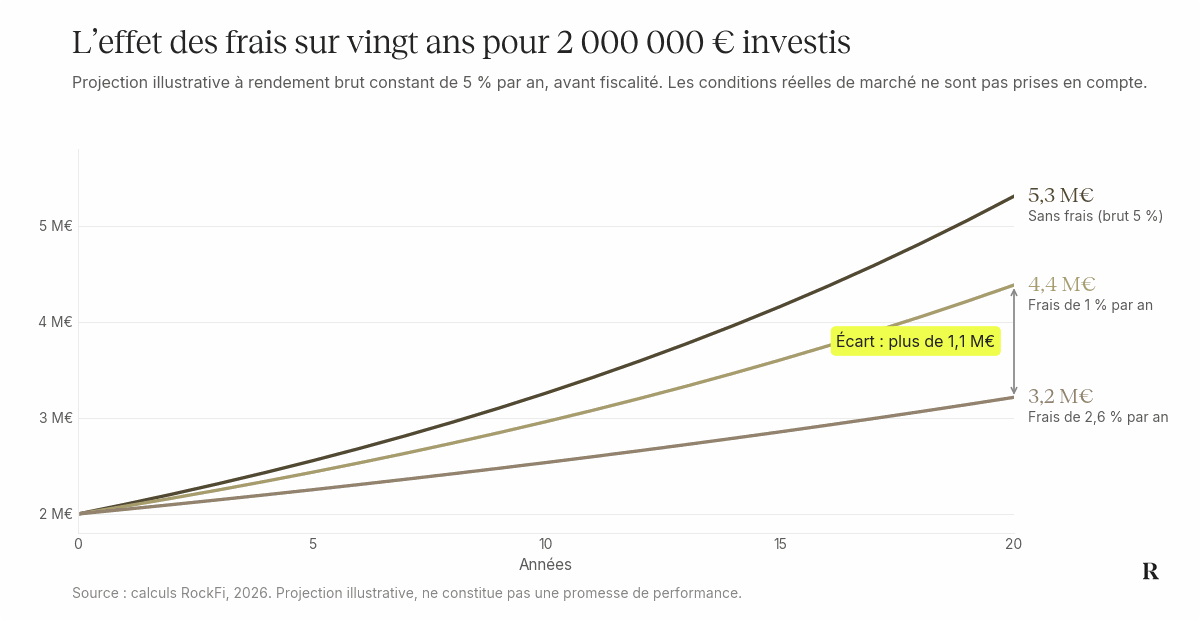
With an illustrative gross annual return of 5% over twenty years, the capital would reach €5.3 million with no fees, €4.4 million with 1% in fees, and €3.2 million with 2.6%.
The difference between perceived and actual fees exceeds €1.1 million, more than half of the initial capital.
What is changing in the industry: transparency is becoming the norm
For the past ten years, the regulatory trend has moved in only one direction: making costs legible, from the MiFID II annual statement in 2018 to the standardised life insurance table in 2022, and the capping of fees for the PEA (equity savings plan) in 2020. The British example shows what is coming next.
"On 31 December 2012, the UK banned retrocessions. The top ten players were private banks. Today, not one of them remains in that group."
Pierre Marin, La Martingale interview.
To be fair to traditional players: private banks offer robust securities custody and broad access to markets, currencies, and Lombard loans, and their bankers are competent.
The issue is not the people, but the model: when remuneration depends on recommended products, advice and sales become blurred.
This subject requires an advisor to provide a price known in advance and decoupled from products. At RockFi, our support is based on a fixed and transparent fee structure, an annual flat fee known from the first meeting, and on an open-architecture selection of over 3,000 assets held in non-retrocession share classes whenever available, for portfolios starting from €250,000.
A client should be able to answer the question "how much does it cost" with a single figure, just as they can answer "how much have I earned".
After the audit: negotiate, simplify, and put to the test
Analysis is only useful if it leads to decisions. Here are five levers, from the simplest to the most structural.
- Negotiate explicit fees, which are best discussed when armed with a quantified comparison.
- Demand non-retrocession share classes, which are mandatory in a discretionary mandate and legitimate in advisory services.
- Replace funds with no demonstrated added value with index funds, which often have fees ten times lower.
- Reduce the number of layers and demand written transparency on foreign exchange and the margins on structured products.
- Put them to the test : since 1 July 2020, transfer fees for a PEA (equity savings plan) have been capped at €15 per listed line, €50 per unlisted line, and €150 in total, and the receiving institution often covers these costs.
Our private advisers, former private bankers, conduct this audit before making any recommendations.
Eight questions to ask your private banker
- What was my total cost last year, across all layers, in euros and as a percentage of my average assets under management?
- How much in retrocessions have you received on my funds, and why am I not invested in clean share classes?
- What proportion of my portfolio is invested in funds managed by your group?
- What margin do you apply to foreign exchange transactions, and can you cap it in writing?
- What is the structuring margin on the structured products offered?
- What is the turnover rate of my portfolio and what brokerage fees has it generated?
- Is my cash earning interest, and at what rate?
- What fees would apply if I were to transfer my assets?
A banker who does not answer these eight questions is already giving you an answer.
Sources
- Autorité des marchés financiers, summaries of SPOT inspections on discretionary management and MiFID II, 2019 and 2020, amf-france.org
- Légifrance, Decree No. 2020-95 of 5 February 2020 on the capping of PEA fees, legifrance.gouv.fr
- Légifrance, Order of 24 February 2022 on strengthening transparency regarding PER and life insurance fees, legifrance.gouv.fr
- European Central Bank, monetary policy decisions, June 2026, ecb.europa.eu
- France Assureurs, 2025 data on life insurance policy management fees
- S&P Dow Jones Indices, SPIVA study, fifteen-year results
Disclaimer
This article is for educational and informational purposes only. It does not constitute personalised investment advice, a recommendation to buy or sell any financial instrument, or tax advice.
The numerical examples are fictitious and illustrative; tax treatment depends on individual circumstances and is subject to change. All investments carry a risk of capital loss, and past performance is not a reliable indicator of future results.
Before making any decisions, please consult an authorised advisor. RockFi is registered with ORIAS under number 23004556 (insurance broker, financial investment advisor, banking operations broker), is subject to the supervision of the AMF and the ACPR, and is a member of Anacofi.